 By
The tape trick costs about four dollars and it tells you more about your roof’s wind resistance than most free inspections. Not the painter’s tape you’re picturing. The kind you seal a window with.
Here’s what happens. You pick a window on the wall that faces your prevailing storm winds. You tape it shut and leave it for the season. If your roof blows off during a hurricane someday, that taped window is the first thing an insurance adjuster asks about, because internal pressurization is what lifts most residential roofs off a home. Wind gets in through one opening, and now you have a balloon instead of a house.
I’m not a roofer. I’ve just spent enough hurricane seasons on the Gulf Coast to know that most roof failures start weeks before the storm makes landfall. If you want to understand how to prevent roof damage from hurricanes, you have to think in layers: what your insurance company will credit you for, what your roof actually tolerates, and what you can still fix after you’ve run out of time. This piece walks through all three.
Your roof’s three defenses during a hurricane
Every roof that survives a major storm does so because three systems held up. Think of it as a sequence, because the first layer is what most homeowners skip entirely.
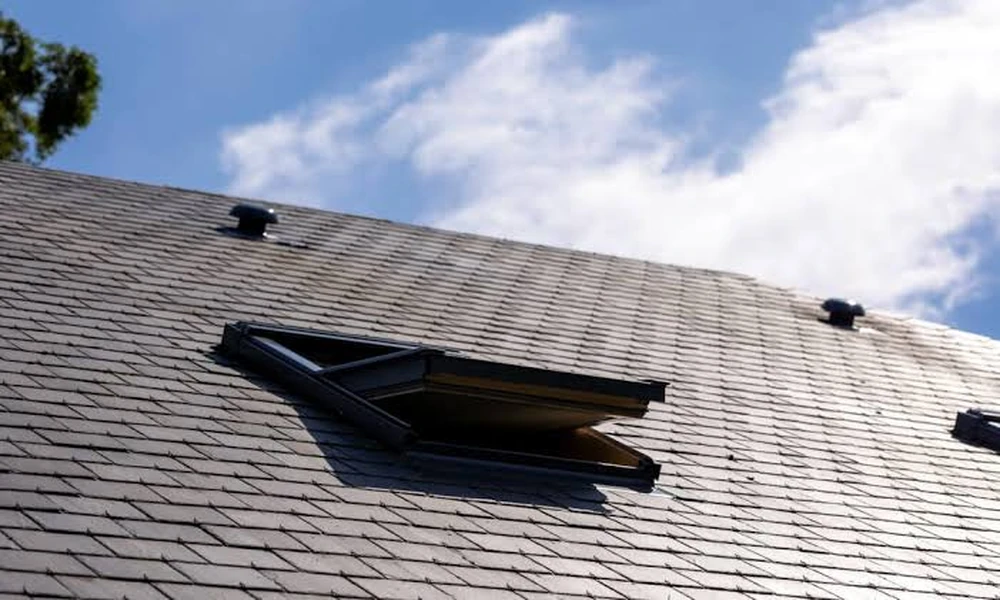
- The seal layer. That’s your covering: shingles, tile, or standing-seam metal. If the edge lifts, wind is inside your attic within seconds.
- The deck layer. Plywood or OSB sheathing, plus the underlayment underneath it. This is the part everybody forgets about until it fails and the ceiling stains show up.
- The connection layer. Nails, straps, clips, and the trusses they hold down. Or, if you live near a coast, your roof-to-wall attachment, which is almost never visible from the ground.
Now think about which of those three you can influence. You can’t easily replace the seal on a 30-year roof without a crew. But you can check for the warning signs before the next storm warning, and you can ask a contractor to walk the deck and connections after the fall season, which I think is the single most underrated winter event on a homeowner’s calendar.
If you’re in South Florida, the pre-season inspection question isn’t optional. Insurance carriers have gotten stricter about age and condition, and they want a paper trail.
Do roofing insurance discounts actually exist, or is that just brochures talking?
They exist, but they’re narrower than the marketing suggests. Wind mitigation discounts are real in most hurricane-prone states, and they’re based on specific inspection criteria: roof covering type, roof deck attachment, roof-to-wall attachment, and secondary water resistance. Whether your policy actually gives you a meaningful percentage depends on your carrier, your deductible structure, and the age of the roof. That’s not a “call and ask for the discount” kind of thing. It’s a documented condition on a form, filled out by a licensed inspector.
Here’s what I’d do if I owned a home in a hurricane zone. Ask a roofer to complete a wind mitigation inspection before storm season, take the form to your agent, and ask directly what credit it produces. If the number feels small, that’s fine. You still have a baseline document showing your roof was in working order before a storm, which is worth its weight in the middle of a claim argument.
Waiting until the forecast turns red
Once a tropical storm watch posts, home supply stores see a run on tarps and plywood. Contractors get booked out for weeks. So a homeowner who is standing on the driveway looking at three missing shingles has two options: call the first company that answers and pay whatever, or wait and hope the next storm doesn’t hit the exposed deck.
That’s the trap. A loose ridge cap is a five-minute repair when your roofer has a free Tuesday. Same ridge cap after a storm warning is a two-week wait, and any crew that shows up fast is billing emergency rates.
My rule is simple. If I see a bent piece of flashing or a shingle in the yard, I call the same week the weather is calm and sunny. I learned that the expensive way after one October storm dropped a limb onto a corner of my parents’ house and the repair wait ran past the next rain. Never again.
What you can genuinely do yourself
Not everything requires a roofer. Here’s what belongs in your hands and what doesn’t:
| Task | Who should do it | Why |
|---|---|---|
| Clearing gutters and checking downspouts | You | Clogged drainage backs water under your eaves. |
| Trimming overhanging limbs | You or a licensed arborist | Branches become battering rams in high wind. |
| Sealing a cracked vent boot or pipe collar | You | Small openings turn into interior water intrusion. |
| Checking attic for water stains or musty smells | You | Both point to a deck or underlayment breach. |
| Replacing lifted shingles or tile | Roofer | Improper reattachment can cost you a claim dispute. |
| Checking roof-to-wall straps | Roofer | Requires attic access, tools, and a trained eye. |
| Sealing or replacing flashing | Roofer | Wrong sealant or wrong lap creates a leak path. |
That last column matters more than the first. The National Institute of Standards and Technology has published post-storm field studies on how wind damage tends to concentrate at edges, corners, and around roof penetrations. Translation: the weak spots are predictable. You don’t need to be a roofer to notice them. You do need to know where to look.
After the storm: what to do in the first 48 hours
Storm passed. Now the first 48 hours decide whether you’re filing a manageable claim or a catastrophe claim.
- Stay on the ground. Do not climb up. Wet roof surfaces are slick, and a fall is a bigger problem than the leak.
- Document everything. Photograph the exterior from multiple angles, then the interior ceiling, walls, and attic access.
- Look for the interior signs. Water stains on the upper-floor ceiling. A dark ring around a recessed light. Musty smell in the attic.
- Call a licensed roofer for evaluation. Ask for a written scope of work, not a verbal estimate.
- Tarp only if safe and approved by your insurer. Many carriers reimburse emergency mitigation. Some want it documented first.
- Call your agent before you authorize major repairs. Scope disputes are easier to resolve when the claim precedes the work.
The National Weather Service is the fastest source for post-storm advisories, flood watches, and wind projections, and the tweet or alert you’ll want is usually posted before any local news segment catches it. Follow them for the storm calendar and your insurer for the claim calendar. They’re two different things.
The five-dollar rule I use every May
One gallon of roof cement. One tube of exterior-grade silicone. One roll of butyl tape. A pair of work gloves. A flashlight.
Under five dollars if you shop at a warehouse store, a bit over if you buy at a hardware store, and every one of those items vanishes from sale the week a storm gets named. Having them in a labeled bin means you act fast instead of standing in a checkout line next to fifty other frantic people.
Call it the May Bin. It’s not glamorous. It’s the difference between tarping your own roof before the second system rolls through and watching your ceiling drop.
When to stop patching and start replacing
I’ll give you a blunt answer. If your roof is past fifteen years old and you’ve already had one leak repaired in the last two seasons, stop treating it as a repair problem. You’re pouring money into a surface that has run out of tolerance, and the next major storm is going to make the decision for you, at a worse price, with a longer wait.
Replace before the next season opens. Ask about a wind mitigation inspection on the new install. Then get back to your regular life, which is what a roof is supposed to let you do.
Now go walk around your house and look at the gutters. If they’re full, that’s your next Saturday.


Comments